Key Takeaways:
- You can learn how to check if a car has a lien for free by combining three things: the title, your state DMV records, and a simple VIN search.
- A lien means a lender or other party still has a legal claim on the car, which can affect registration, financing, resale value, and even lead to repossession if the debt isn’t paid.
- Before you buy or sell, always match the VIN on the car, title, and paperwork, then run it through a trusted tool like the Instant VIN Reports VIN decoder to confirm the vehicle’s identity.
Buying or selling a used car should never feel like a gamble, yet according to the Federal Reserve Bank of New York, Americans owe more than $1.6 trillion in auto loan debt in the first quarter of 2026, meaning millions of vehicles on U.S. roads are still financed.
Because millions of financed vehicles remain on the road, verifying whether a lien has been released is an important step before purchasing a used vehicle.
This guide shows you how to check if a car has a lien for free using practical, real-world steps so you can protect your money and avoid unpleasant surprises at the DMV.
What a Car Lien Is and Why It Matters
A vehicle lien is a legal claim that allows a lender or another authorized party to retain a financial interest in a vehicle until a debt has been satisfied. The most common example is an auto loan, where the lender is listed as the lienholder on the vehicle's title until the borrower pays off the loan.
However, financing isn't the only reason a lien may exist. Depending on state law, mechanic's liens, tax liens, or court-ordered liens may also be recorded against a vehicle. For buyers and sellers, understanding the type of lien matters because each affects ownership, title transfer, and registration differently.
If you skip this step and never learn how to check if a car has a lien, you’re not just missing “extra info.” You’re taking the risk that the lender, not you, is the one with real control over the car. That can affect your ability to register it, keep it, or sell it later.
How Car Liens Work in Simple Terms
A lien serves as a safety net for lenders when financing a vehicle, which becomes collateral for the loan. Here’s the typical process:
- You finance a car, and the title lists you as the owner and the lender as the lienholder.
- You make monthly payments; if you stop, the lender can repossess the vehicle due to their lien.
- Once the loan is paid off, the lender issues a lien release, and the DMV updates the title to remove the lienholder.
In many states, the lien is noted on the title or in the DMV's electronic system, indicating any outstanding debt.
How to Check If a Car Has a Lien: What Really Works
Checking for a lien starts with understanding where lien information actually comes from. Some sources reflect the car’s legal status in real time, while others are meant only to flag potential issues before you dig deeper. Not every lien check gives the same information. See the table comparison below.
| Method | Current Lien | Previous Lien |
|---|---|---|
| Title | Yes | No |
| DMV | Yes | Availability of historical lien information varies by state. Many DMVs only provide the vehicle's current title status. |
| Lender | Yes | No |
| VIN Report | Yes | Often Yes |
The most reliable lien checks come from title records, VIN-based verification, and state motor vehicle databases. Free steps can help with early screening, but they should support (not replace) the checks that determine whether a lien legally exists.
Free Ways to Screen for Possible Liens
There are several practical steps you can take that don’t cost anything except a bit of time and attention. These are your first line of defense before you even consider paying for anything.
Method 1: Use Free VIN Tools for Basic Verification
A growing number of services let you enter a VIN and see a basic snapshot of the vehicle at no cost. These free tools often give you:
- Basic vehicle specs (e.g., year, make, model, engine)
- Recorded mileage at sales/auctions
- The available data preview of the deeper history that can be unlocked in a paid report
You can start with a free VIN lookup or basic check with our VIN decoder to ensure the VIN is valid and matches the car in front of you. It’s a simple way to sanity-check the vehicle details before you dig deeper or spend money.
At this stage, your goal is not to get every detail. Your goal is to see whether anything looks obviously wrong, like the car has a mismatched model and inconsistencies with what the seller claims.
Method 2: Talk to the Seller and Ask for Proof
When you buy a used vehicle, you can also ask the seller direct questions. For example:
- Did you finance this vehicle?
- Is there an outstanding loan on it right now?
- Do you have the original title and any lien release or payoff letter?
A genuine, organized seller should be able to show at least one of the following:
- A title that shows no lienholder in the lien section
- A lien release from the lender, if the loan was paid off
- Current registration and loan paperwork that matches their name
You don’t pay anything for this step, but it already filters out many risky situations.
A defensive seller isn't automatic proof of fraud. But if they refuse to show the title, dodge questions about financing, or can't explain who holds the loan, slow the transaction down. Those are warning signs worth investigating before money changes hands.
Keep in mind that this step can take time, and sellers may forget about old loans or misunderstand their lien status. That’s why these checks are useful for screening, not final confirmation.
Method 3: Look Closely at the Title
If it’s your own car and you’re wondering how to check if my car has a lien, pull out the title and registration you already have. Many owners are surprised to see that the lender is still listed there even though they “thought” everything was taken care of.
In many states, the title itself will tell you if a lien exists. Look for a section labelled something like:
- Lienholder
- Secured party
- Legal owner
If a bank, credit union, finance company, or other party is listed there, that’s a sign that there is or was a lien recorded. If it says “None,” or the section is blank, the title may be clear, but you still confirm through other steps later.
This visual check is free, quick, and gives you a first snapshot of the car’s legal status.
Why Free Lien Checks Sometimes Miss Important History?
Once you have performed the free checks and the vehicle looks promising, you should prepare to make a small investment to get the definitive answers. If free checks leave unanswered questions, a vehicle history report can provide additional context before you complete the purchase.
Full Vehicle History Reports:
Free tools and DMV lookups each have their strengths, but they can still leave gaps. This is where a paid vehicle history report comes into play. It pulls together data from multiple sources to give a wider view of the car’s past.
You can use online tools like Instant VIN Reports. Here is what you can get, side by side with other providers:
| Feature | Carfax | InstantVINReport | AutoCheck |
|---|---|---|---|
| Price per Report | $49.99 Expensive | $19.99 Affordable | $29.99 Fair |
| Auction Record Photos | No | Yes | No |
| Vehicle Market Value | Yes | Yes | Yes |
| Full Vehicle Specifications | Partial Data | Complete Details | Partial Data |
| Original Window Sticker | No | Yes | No |
| Classic & Vintage Vehicle Support | No | Yes | No |
| Maintenance & Service Insights | Yes | Yes | Yes |
| Ownership Record History | Yes | Yes | Yes |
| Accident Records | Yes | Yes | Yes |
| Title Brand Check | Yes | Yes | Yes |
| Salvage Title Report | Yes | Yes | Yes |
| Ownership Timeline Map | No | Yes | No |
| Recall Notices | Yes | Yes | Yes |
| Heavy-duty truck and trailer VIN support | No | Yes | No |
| ATV and Motorcycle VIN support | No | Yes | No |
Combining a detailed VIN report with DMV records and your own paperwork checks gives you a much stronger picture than any single free step alone. The cost is usually modest compared to what you stand to lose if you buy a car with hidden problems.
State DMV/BMV Title Searches:
Most state Departments of Motor Vehicles charge a minor fee (up to $25) to run an official title and lien search using the VIN. This data comes directly from the state’s authoritative registry and provides the most current, official record of any active lienholders.
Why You Must Check for Liens Before You Buy or Sell
Used vehicles represent the majority of annual vehicle sales in the U.S., making title verification one of the most common due diligence steps for buyers. Failing to verify the lien status is a gamble with your finances. If you decide to skip this check, the consequences can be costly and immediate.
You Inherit the Debt
If the car is taken back or can’t be legally titled, you can end up paying twice: once to the seller, and again in legal costs or settlement negotiations. Even if you manage to keep the car, resolving the lien may require paying off a balance that should never have been your responsibility.
Risk of Repossession
If the debt behind a lien isn’t paid, the lienholder can repossess the vehicle. The lien stays attached until the debt is settled and properly released.
Hidden liens are especially risky. If you buy a car without checking the title or running a VIN check, you might not know a lender still has a claim on the vehicle. If the loan is in default, the lienholder can repossess the car, regardless of what you paid the seller.
Title transfer trouble
In many states, you can’t get a new title fully in your name if a lienholder is still listed. The DMV’s system will show that someone else has a legal interest, and they may refuse to issue a clear title until the lien is released.
Because of these risks, consumer advisers and auto finance experts repeatedly warn people to verify lien status when buying a used car, not just rely on the seller’s word.
For sellers, ignoring an old lien is just as dangerous. If your loan was paid off years ago but the lien release was never properly recorded, you may run into problems when a buyer tries to register the car.
What to Do If You Find a Lien on a Car
Discovering an active lien on a car you’re planning to buy should not make you panic, but it must make you pivot. It means the transaction just became more complex, and you need to proceed with extreme caution and clear boundaries.
If You’re Buying the Car
You essentially have three courses of action when faced with an active lien, and two of them involve significant risk mitigation.
Require Seller Payoff:
This is the simplest and safest option for you. You require the seller to pay off the outstanding loan and provide you with an original, official lien release document before you hand over any purchase funds. You then finalize the sale with the officially clear title in hand. Waiting a few extra days for this paperwork is better than risking your entire investment.
Direct Payoff to the Lender:
If the outstanding loan balance is less than the purchase price, you can coordinate a direct payoff. You meet the seller at the lienholder’s bank, pay the lender the payoff amount directly, and then pay the remaining balance of the agreed-upon price to the seller. The lien is cleared immediately by the lender, and the paperwork can be initiated for transfer. This must be meticulously documented.
Walk Away:
If the seller is unable or unwilling to facilitate the payoff through one of the verified, transparent methods above, you must be prepared to walk away from the deal. There are simply too many risks associated with relying on verbal promises about financial commitments.
If You Already Bought the Car and Discover a Lien Later
If you purchased a vehicle and later a lender comes forward claiming a security interest, your immediate action is crucial.
Contact Seller and Lender:
Immediately gather all your purchase documentation and contact both the seller and the lender named in the lien. You must establish the facts of the remaining debt and use your bill of sale as proof of your purchase date.
Consult Legal Counsel:
If the lender threatens repossession or if the seller is unreachable and you suspect fraud, consult a local attorney specializing in consumer fraud or auto transactions. They can best advise you on your rights and the next legal steps.
Use Your Records as Proof:
Your documented checks (VHRs, DMV printouts, title copies) will demonstrate your good faith and due diligence, which is necessary if you end up in a legal dispute.
How to Remove a Lien from a Car Title
If you’re the owner and you’ve paid off your loan, here’s how to get that lien removed from your title:
- Confirm your loan is fully paid off — check your final loan statement or call your lender
- Get a lien release letter — the lienholder must sign off on the title or provide a letter of lien release on company letterhead
- Bring it to the DMV — take the original title, lien release letter, proof of payoff, valid ID, and the title fee ($15 to $33 depending on your state)
- Receive your clean title — once processed, you’ll receive a title free and clear of any liens
Conclusion on How to Check If Your Car Has a Lien
At first glance, how to check if a car has a lien sounds like a technical question. Once you understand the stakes, it becomes something much more personal. It’s about making sure the car you buy, drive, and rely on every day is truly yours, without hidden strings attached to a bank or a past owner.
By taking the time to:
- Match the VIN across the car, title, and records
- Read the title carefully
- Use state systems and, when needed, a full vehicle history report from a service like Instant VIN Reports
The time you invest in verifying the title’s status will protect your money, secure your legal ownership, and ultimately ensure you enjoy your new vehicle without the looming threat of inherited debt. Decode your VIN and confirm the lien status before you buy.
FAQs About How to Check If a Car Has a Lien for Free
How to find out if there is a lien on your vehicle?
To find out if there is a lien on your vehicle, check the vehicle title first. If a bank or lender is listed as a lienholder, the lien is active unless a release is recorded. For confirmation, verify the VIN with any lender you’ve used and compare everything with a recent VIN-based history report from a trusted provider such as Instant VIN Reports.
How to check if a lien is on a vehicle?
To check if a lien is on a vehicle, use a three-step check:
- Read the physical title and registration to see whether a lienholder is printed.
- Run a VIN search with your DMV or through the national title system they connect to, which will show the current title and any recorded liens.
- Cross-check with a vehicle history report to see when the lien was first reported and whether any release is noted.
How to make sure there is no lien on a car?
To be as certain as possible, you need both paperwork and official confirmation. The title should show no lienholder, you should have a lien release (if there was ever a loan), and the DMV’s current record for that VIN should list the owner only, with no active lien.
Can I check for a lien on a car for free?
Yes. You can perform several free checks before paying for a detailed report. Review the vehicle title, ask the seller for a lien release or payoff documents if applicable, and verify that the VIN matches the title and registration. These steps can identify many potential issues, although official title records or a comprehensive vehicle history report may provide additional details.
How to see if a car is paid off?
If the car was financed, it’s “paid off” when the loan balance is zero, and the lienholder has issued a lien release and removed their name from the title. Lenders are generally required to send a release or notify the DMV once the debt is satisfied. Ask the lender for a payoff letter or confirmation, then verify with the DMV that a clear title is now in your name alone.
What happens if I buy a car with a lien?
Buying a car with an active lien can delay the title transfer and, in some cases, expose you to repossession if the previous owner's loan remains unpaid. Before completing the purchase, confirm how the lien will be satisfied and obtain documentation showing the lender has released its legal interest in the vehicle.
How do liens affect vehicle ownership?
A lien does not prevent you from driving the vehicle, but it gives the lienholder a legal financial interest until the debt is paid. An active lien can affect title transfers, refinancing, selling the vehicle, and, if the loan defaults, may allow the lienholder to repossess the car.
Can a car be registered with a lien on it?
Yes. In most states, a vehicle can be registered while an active lien exists because registration and ownership financing are separate matters. However, transferring ownership or obtaining a clear title may not be possible until the lien has been released according to your state's requirements.
How to get a lien release from a lender?
After the loan has been paid in full, the lender issues a lien release or notifies the state motor vehicle agency electronically, depending on state procedures. Keep the lien release with your records and submit any required paperwork to the DMV so the title can be updated to remove the lienholder.
What is a secured party on a car title?
A secured party is the lender or organization that has a legal financial interest in the vehicle because it financed the purchase or holds another valid claim. On many titles, the terms secured party and lienholder mean the same thing.
What is a title number and where to find it?
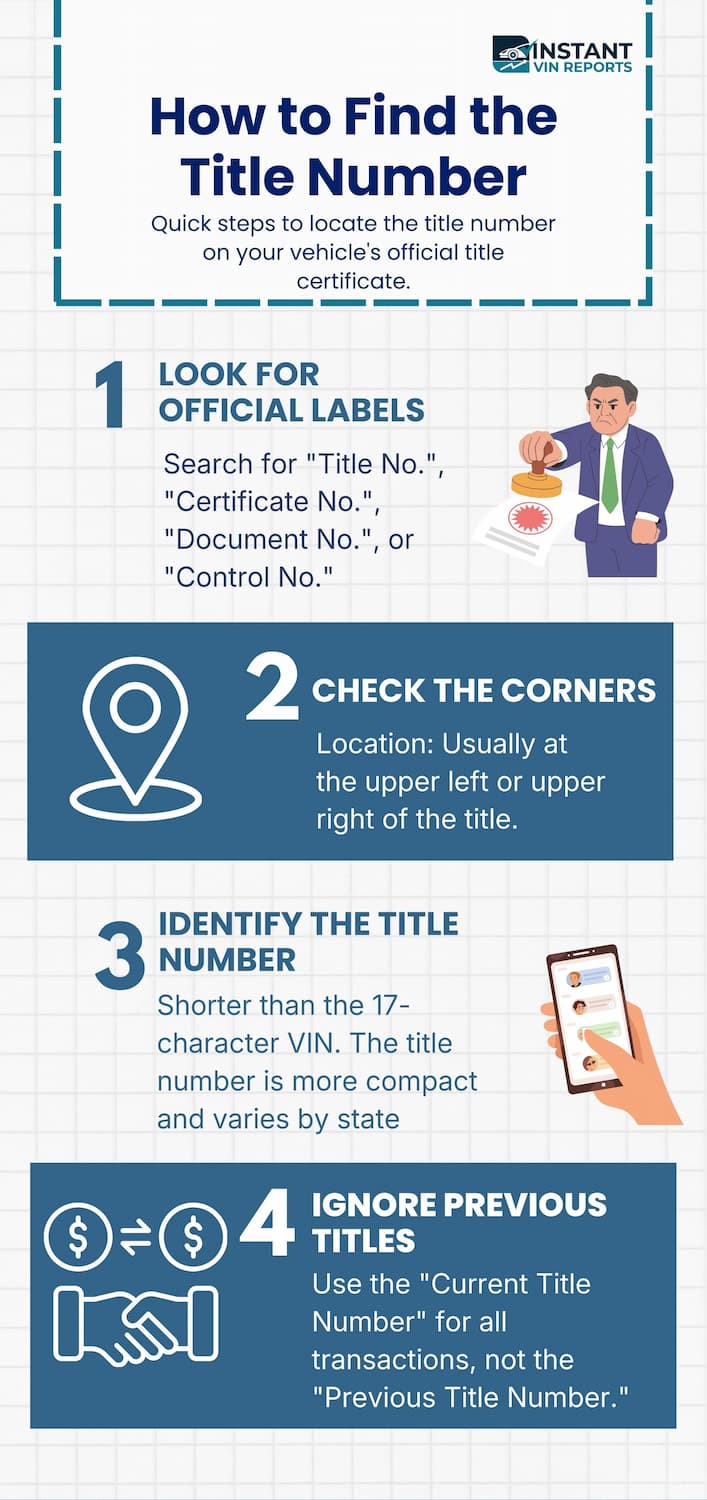
A title number is the unique identification number assigned to a vehicle's certificate of title. It is usually printed near the top of the title document, although the exact location varies by state. This number helps the DMV identify the specific title record for the vehicle.
How to check to see if a car title is clean?
A “clean” title usually means no major brands, such as salvage, rebuilt, or flood. You can check this by pulling the title record from your DMV and by running a VIN through a vehicle history report, which summarizes title brands reported by states and insurers.